

5 Effective Bank Debt Collection Strategies that Minimise Non-performing Loans
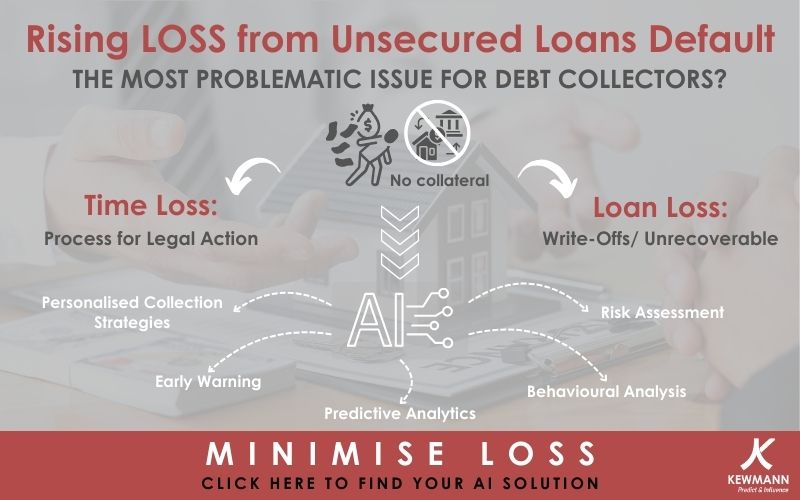
Lending is an important source of revenue for banks, but every loan also carries the risk that a borrower may become unable or unwilling to meet repayment obligations. The challenge is not simply recovering overdue debt after it becomes delinquent. Effective bank debt collection increasingly starts earlier, by identifying changes in customer behaviour, understanding why repayment risk is increasing and selecting an appropriate intervention before the account progresses into a non-performing loan.
Current banking data shows why proactive collection remains important even when overall asset quality appears healthy. Bank Negara Malaysia reported in its July 2026 update on banking-sector asset quality that Malaysia’s gross and net impaired loan ratios remained at 1.4% and 1.0%, supported by a loan-loss coverage ratio of 124.6%. In Europe, the European Banking Authority’s Spring 2026 Risk Assessment Report found that aggregate NPL ratios remained low, but vulnerabilities were more concentrated in areas such as SMEs and consumer credit, where NPL ratios were approximately 4.4% and 5.4% respectively.
This means a good collection strategy should not wait for the customer to become seriously delinquent. Banks can use AI, Machine Learning, behavioural data and early-warning models to identify changing repayment risk sooner, prioritise the right accounts and choose interventions that improve recovery while treating customers fairly.
Traditional collection process
- Credit Assessment – Credit assessment in traditional processes involves manually checking applicants’ credit behaviour using internal or external credit scoring systems.
- Loan Approval and Payment Journey – After approval, customers begin their payment journey, requiring organisations to monitor payments for timely collection.
- Late Payment Detection – Late payments are identified and logged in a collection database to prepare for follow-up actions.
- Follow-Up with Default Customers – Defaulting customers are contacted by desk collectors, and in severe cases, field collectors may engage directly.
- Debt Recovery – Unpaid debts may be escalated to third-party collection services to recover outstanding amounts and manage delinquency.
Problems in traditional debt collection/ recovery
- Time-consuming and insufficient workforce – manual credit assessment is time-consuming and it may cause erroneous during the approval process due to human error; manual collection process that purely relies on human resources to monitor and track debtors’ payment and follow up all the debtors may experience insufficient workforce when there is an unexpected increase in defaulters.
- One-size-fits-all communication methods – not all defaulters have the same profile, background & behaviour, thus a cookie-cutter approach that often adopted by lenders may not bring significant effect.
- Inappropriate tones and actions – the debtors may feel threatened by the desk collectors or field collectors with the harass typed calls and messages at an inconvenient time.
- Customer’s inability to pay – continue to harass the debtors persistently by mass calling or texting instead of coming up with a guided solution to lead the debtors who are in financial difficulties will not encourage the debtors or customers to pay on time.
5 strategies should be applied to enhance debt collection
-
Monitor Customer Behaviour Continuously
Customer behaviour often begins to change before a payment is missed. Transaction frequency may decline, deposit patterns may change, account balances may fall or the customer may begin using available credit differently. When this information is analysed together, it can provide an earlier indication that repayment risk is increasing.
A data-driven collection process brings together relevant information across the customer relationship rather than analysing the overdue loan in isolation. Structured data such as repayment history, balances and transaction behaviour can be combined with engagement, service and other permitted data to create a more complete view of the customer’s current situation. Machine Learning can then identify patterns associated with higher default risk and help determine which accounts require attention first.
This does not mean that every change in customer behaviour should trigger aggressive collection activity. The purpose is to identify when intervention may be useful and determine what kind of intervention is proportionate. A customer showing minor changes may only require a reminder, while a customer displaying several indicators of financial stress may benefit from earlier engagement and discussion of available repayment options.

-
Use Alternative and Current Data to Improve Collection Decisions
Historical repayment information remains important, but collection decisions based only on historical data may miss what is happening to the customer today. Economic conditions, employment changes, business performance, market disruption and sector-level stress can alter repayment capacity much faster than traditional review cycles.
Alternative data can add useful context where its use is appropriate, lawful and relevant to the collection decision. This may include internal behavioural information, digital engagement signals, current business indicators or external economic and industry data. The objective is not to collect as much information as possible. It is to identify which additional data improves the bank’s ability to distinguish temporary payment difficulty from more serious deterioration.
Data quality matters just as much as data quantity. Outdated, duplicated or poorly connected data can lead to inappropriate collection decisions, even when sophisticated AI models are used. Current and trusted data allows predictive analytics to produce more useful insights, while human collectors still need sufficient context to understand why a customer has been prioritised.
-
Build Early-Warning Models Before Delinquency Becomes NPL
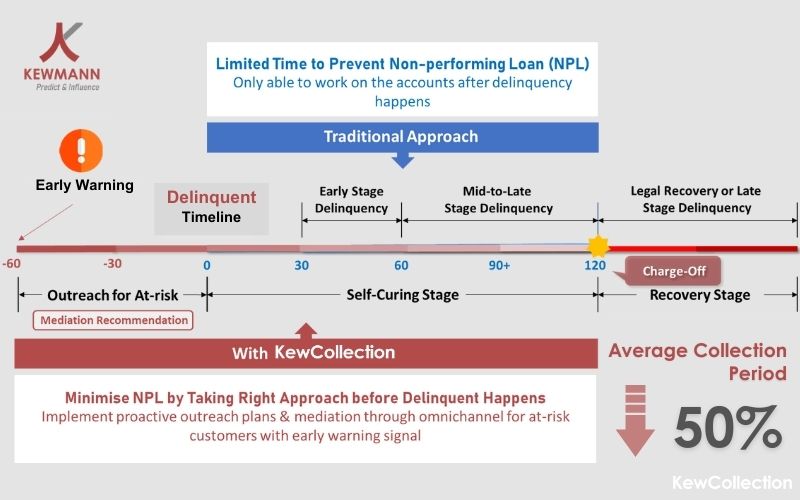
Traditional collections often rely on rules such as days past due, missed-payment counts or fixed account thresholds. These remain useful indicators, but they are lagging signals because the deterioration has already happened by the time the threshold is reached.
Dynamic early-warning models can combine repayment behaviour, transaction changes, customer characteristics and current risk indicators to estimate whether an account is becoming more likely to default. Instead of placing every customer into the same fixed collection sequence, the bank can segment accounts based on repayment risk, propensity to pay and the type of intervention most likely to be appropriate.
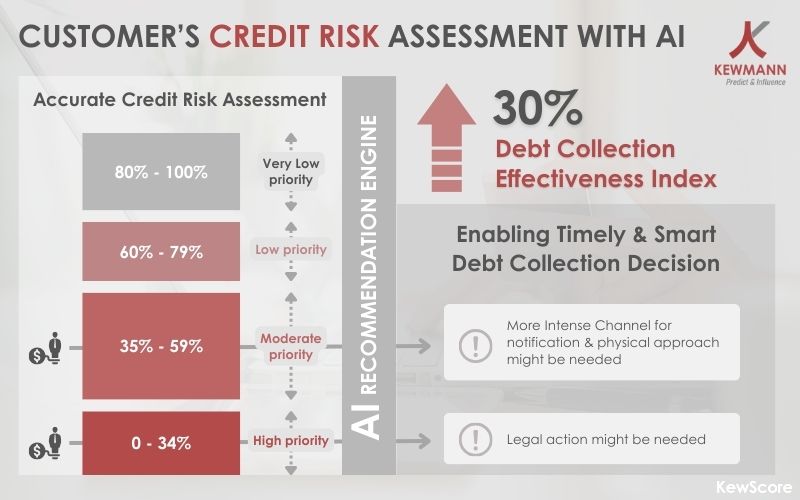
This is particularly useful when linked to credit-risk assessment earlier in the lending lifecycle. Existing AI-driven implementations have reported more than 90% accuracy in credit-risk scoring, over 20% faster approvals and more than 65% less manual involvement in credit evaluation. The same principle of using dynamic and alternative information can continue after approval, helping lenders monitor how customer risk changes over time rather than relying only on the original credit decision.
For a deeper discussion of this approach, the relationship between AI, alternative data and dynamic credit-risk scoring before loans deteriorate is particularly relevant to NPL prevention. The important shift is from asking only whether a borrower was creditworthy at the time of approval to continuously understanding whether that borrower’s ability to repay is changing.
-
Recommend the Right Repayment or Mediation Option
When a customer begins experiencing genuine financial difficulty, repeatedly sending the same payment reminder may not improve recovery. The more useful question is whether a different repayment arrangement can increase the probability of a sustainable resolution while remaining consistent with the bank’s policies and regulatory requirements.
AI-assisted recommendation models can help collectors assess factors such as repayment history, current affordability, customer behaviour and previous engagement to identify appropriate options. Depending on the institution’s policies, these might include revised payment schedules, temporary adjustments or other structured arrangements. The recommendation should support the collector’s judgement rather than automatically impose a financial decision on the customer.
This approach is increasingly aligned with the direction of modern collections. A March 2026 PwC Malaysia analysis of AI-powered banking recovery describes a shift from simply chasing delinquency towards using behavioural and transactional signals to predict repayment propensity, recommend next-best actions and keep human judgement within the decision process. The same analysis highlights that collection strategies increasingly need to consider not just financial recovery, but also customer trust, regulatory compliance and consistency of treatment.
The operational impact can also be meaningful. Existing collection implementations report 2x more debt collection efficiency, over 60% successful resolutions from mediation alerts and more than 20% lower NPLs through earlier intervention. These results reinforce an important point: effective collections are not only about increasing the number of contacts. They are about improving which customers are contacted, when they are contacted and what resolution is offered.
-
Apply Behavioural Science Throughout the Collection Journey
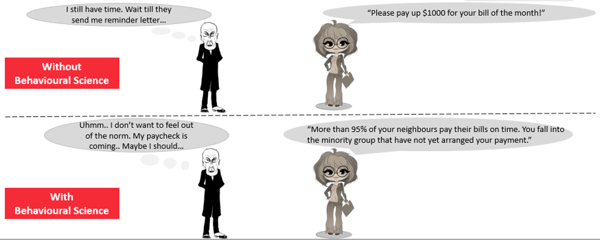
Debt collection is ultimately a human interaction. Customers do not respond only to the financial value of an outstanding payment. Timing, wording, channel, perceived fairness and the way repayment choices are presented can all influence how a customer responds.
Behavioural science can therefore complement analytics by helping banks design communication around actual customer behaviour. Different customer segments may respond better to different channels, message framing or timing. A reminder for a customer who normally pays on time should not necessarily look the same as communication for a customer experiencing repeated financial stress.
Personalisation should not become manipulation or excessive pressure. Bank Negara Malaysia’s Fair Treatment of Financial Consumers policy specifically strengthens expectations around fair and equitable treatment, including appropriate support for vulnerable consumers. For AI-driven collection processes, this makes governance particularly important because automated recommendations and communication should remain explainable, proportionate and consistent with the customer’s circumstances.
More recent collections thinking follows the same direction. PwC Malaysia’s 2026 analysis notes that behavioural signals such as contact history and engagement patterns can strengthen recovery prediction, while personalised digital engagement can help banks determine when to contact a customer, which channel to use and what type of repayment option may be appropriate. The role of AI is therefore not simply to send more messages. It is to help the collection team engage more intelligently and consistently.
By apply behavioural science in the system, you are able to create great design personalised messages and channels to elicits positive responses from the debtors. A government tax department added one sentence in the tax notice based on the behavioural recommendation and it resulted in 66% more tax collection.
The Future of Bank Debt Collection: Earlier, Smarter and More Human
Bank debt collection is moving away from a process that begins only after a customer misses a payment. The stronger model combines early-warning indicators, current customer data, dynamic risk scoring, personalised repayment recommendations and behavioural science so that banks can intervene before financial difficulty becomes more severe.
AI can make this process faster by continuously analysing account and behavioural signals, prioritising cases and recommending next steps. However, the purpose of automation should not be to remove judgement from collections. The greatest value comes when AI helps collectors understand each customer’s circumstances more quickly, while people remain responsible for exceptions, sensitive cases and decisions that require empathy or accountability.
The objective is also broader than maximising short-term repayment. A sustainable collection strategy should reduce non-performing loans, improve recovery efficiency and protect the customer relationship at the same time. When banks can identify risk earlier and offer an appropriate resolution sooner, debt collection becomes less about chasing overdue payments and more about preventing manageable financial difficulty from becoming a larger problem.
For insights on leveraging technology in combating financial crimes, explore our blog on “4 Innovative Safeguards: Technology’s Role in Anti-Money Laundering for Insurance“
Discover more to get a hint on your upcoming technologies intervention: